

 Facebook
 X
 Pinterest
 Copy Link
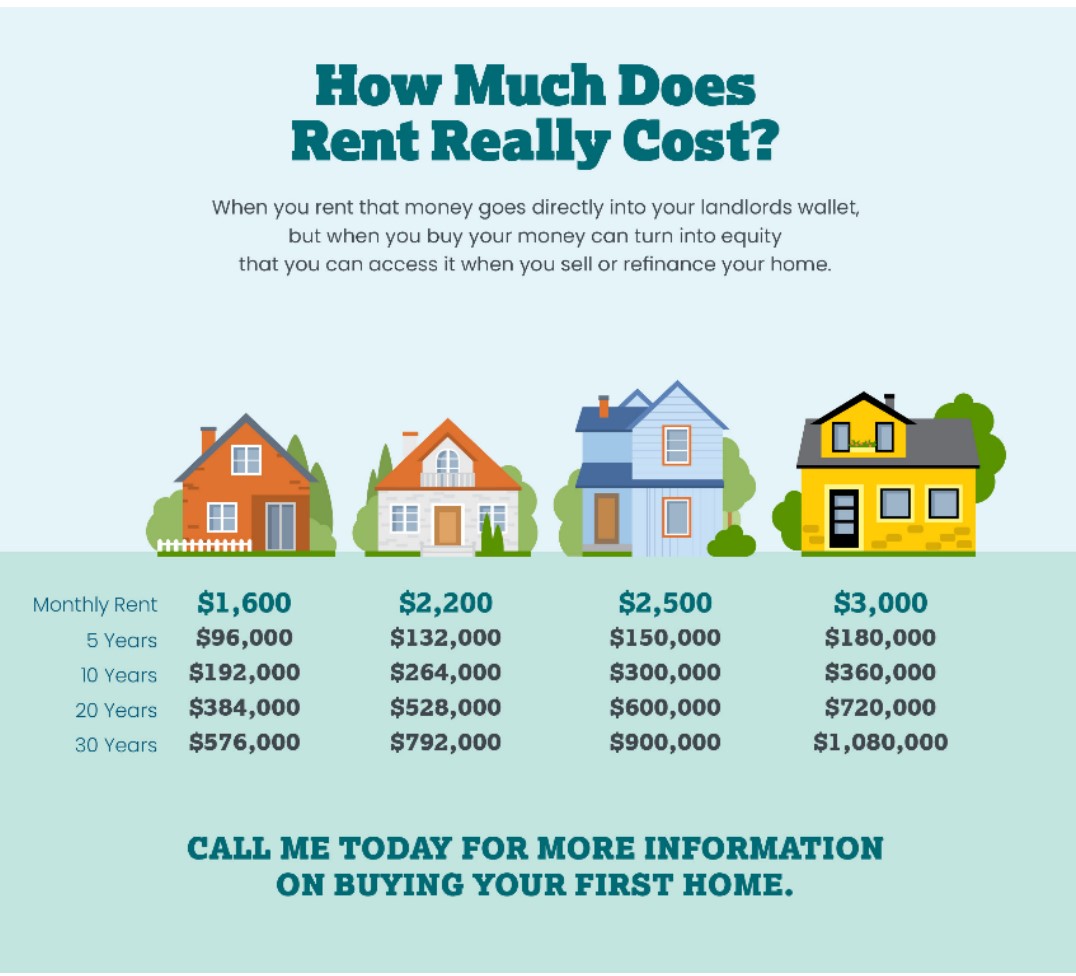 Let me start this discussion with my personal story. When I decided to leave my marriage after 20 years, I was starting over with very little money and average credit. Buying a home on my own felt impossible but I knew if I was ever going to build any wealth to pass on to my children, I needed to put my head down and do what I needed to do no matter how hard it was. Guys, I STRUGGLED, but I made it work! I put in everything I had and (even some borrowed) to purchase my first home by myself in 2011. Sure, the monthly payment felt a high for me, but determination and a few tweaks (including a lot less Starbucks for a while) and I was able to do it. Fast forward 9 years and that same property is an investment property for me with a very positive cash flow each month. It is POSSIBLE! You don’t need perfect credit with 20% down to make your dreams come true, you just don’t.
I’ve had some conversations with a couple of my preferred lenders and want to pass along their knowledge. Aaron Hoy, one of my preferred lenders at Capstone Home Loans, shared with me “Most first-time home buyers think you need 20% down, yet several 0% and low-down options are available.”
- You may qualify for a low-down payment of 3% with Fannie Mae Home Ready or the Fannie Mae Home Possible. This is to help not only with lower down payment yet also helps to lower interest rates and PMI.
- Federal Housing Administration (FHA) only requires 3.5% down and typically will allow lower credit scores and slightly lower rates versus conventional.
- The Veteran Affairs (VA) loan allows current service members, veterans, and reservists to purchase a home with 0% down with no PMI and qualifies borrowers based on residual income versus debt-to-income ratios.
- United State Department of Agriculture (USDA) Allows for 0% down; there is a small monthly mortgage insurance requirement and an upfront fee of 1%, typically lower than FHA and sometimes conventional financing. This loan is intended for rural housing and has income limits.
Janelle Steinberg, another of my preferred lenders at American Pacific Mortgage (APM), answered the FAQ of how will my credit impact interest rates when I purchase, and should I be concerned if more than one lender pulls credit? She advised:
- Credit scores impact what your final rate is. The higher the credit score, typically the lower the rate. If there are two buyers, we take the average score of both borrowers.
- We are required to pull credit for an official preapproval on all loans. There are two type of credit pulls- one is called a “soft credit pull” and one a “hard credit pull”. The soft pull will tell us a credit score from one credit bureau (there are 3 bureaus) which allows us to do general pricing on rates. A hard credit pull is “the real deal”. This means all three credit bureau’s information is provided to us and we can officially complete the pre-underwrite on the file.
Is it always easy? No.
Is it always possible? No.
Is it worth checking into and trying? YES! If I can answer any questions, just reach out. 😊


 Yes, interest rates are 7.5%. Yes, they were 2.5% eight months ago. You know what else was happening eight months ago? Houses were going for hundreds of thousands of dollars higher than they were worth. Buyers were having to waive inspections and hope the house they bought wasn’t going to cost them significantly more than they already paid. Buyers were also getting their hopes up only to learn their life savings wasn’t enough to purchase anything that would fit their families’ needs. But because the interest rates were so low, no one seemed to care. Now that interest rates are higher (and might I add, they’re very average over the history of interest rates), people are scared to waste their money. WRONG….
 In the months of July and August, the Seattle area real estate market has seen a near screeching halt in buyer activity. Buyers are tired of the extremely competitive market they’ve been fighting during the pandemic, interest rates have risen, and everyone wants to be out in the sunshine that finally decided to show up in the PNW. The market is very unpredictable, no wonder you’re confused. Even trained realtors who are living and breathing the market every day are unsure of what will happen with each listing. But it’s not all bad….

